What Happens If the At-Fault Party Doesn’t Have Car Insurance?
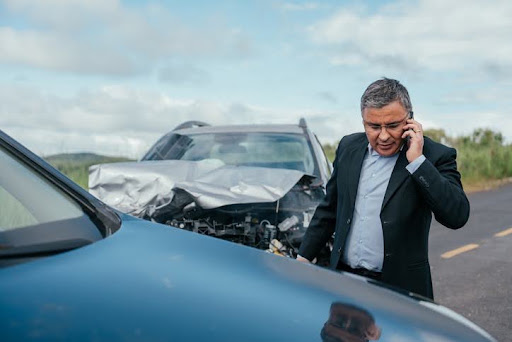
A car crash creates immediate stress, but discovering the driver who hit you doesn’t carry auto insurance adds severe frustration. Whether your collision happened on I-75 in Atlanta, along Mulberry Street in Macon, or on Abraham Baldwin Agricultural College routes in Warner Robins, dealing with an uninsured driver presents major legal hurdles.
In Georgia, driving without minimum liability insurance is illegal, yet thousands of uninsured drivers take to the roads every day across Fulton, DeKalb, Bibb, and Houston counties.
Georgia law gives you several paths to pursue compensation, even when the at-fault driver carries no coverage at all. At Seay/Felton LLC Trial Lawyers, our team helps crash victims handle complex insurance claims to ensure medical bills, property damage, and lost wages do not come out of your own pocket.
Call Seay/Felton at 404-902-6444 or contact us online for a free consultation. You do not pay attorney fees unless we recover compensation for you.
Here is what happens when an at-fault driver has no insurance in Georgia and the exact steps you should take to protect your rights.
Georgia Insurance Laws and the Uninsured Driver Problem
Under O.C.G.A. § 33-34-4, Georgia law mandates that all vehicle owners carry minimum liability insurance coverage:
- $25,000 for bodily injury per person.
- $50,000 for bodily injury per accident.
- $25,000 for property damage per accident.
When an uninsured driver causes a crash, law enforcement officers issue citations for driving without insurance. While offenders face criminal penalties including fines, license suspensions, and potential jail time, these criminal sanctions do not automatically cover your emergency room care or vehicle repairs. You must seek financial compensation through civil insurance channels or direct legal action.
Tap Into Your Uninsured Motorist (UM) Coverage
Your primary source of recovery after an accident with an uninsured driver is your own auto insurance policy: specifically, Uninsured/Underinsured Motorist (UM) Coverage.
How UM Coverage Works in Georgia
Under O.C.G.A. § 33-7-11, insurance companies in Georgia must include UM coverage in auto policies unless you explicitly reject it in writing.
- Add-On UM Coverage (Recommended): Stackable coverage that adds your UM policy limits on top of any existing liability coverage available.
- Reduced UM Coverage: Covers only the difference between the at-fault driver’s insurance limits and your own UM policy limit.
UM coverage steps into the shoes of the missing liability policy. It pays for your medical treatment, lost wages, pain and suffering, and property damage up to your selected policy limits.
What If You Don’t Have UM Coverage?
If you rejected UM coverage in writing or you’re not sure what your policy includes, you still have options. Your health insurance can help cover medical bills while your attorney pursues the at-fault driver directly or investigates other liable parties, such as an employer or vehicle owner. Reviewing your policy documents with an attorney early on can clarify exactly what coverage you carry and what avenues remain open.
Can You Sue the At-Fault Driver Directly?
Yes, you can file a personal injury lawsuit directly against an uninsured driver in a Georgia civil court. However, our legal team always evaluates a driver’s financial standing before pursuing this route.
Drivers who operate vehicles without insurance rarely possess significant personal assets, liquid savings, or real estate. If a court enters a monetary judgment against an uninsured individual, collecting that money can prove difficult or impossible. A personal injury attorney evaluates all available avenues, including third-party liability, to locate valid sources of financial recovery.
Other Potential Sources of Compensation
When the driver lacks insurance, a thorough investigation often uncovers alternative policies or liable parties, and identifying every source early can make a meaningful difference in what you ultimately recover.
- Resident Family Member Policies: In Georgia, you may stack UM coverage from auto policies owned by relatives living in your household.
- Employer Liability: If the uninsured driver was working or operating a commercial vehicle at the time of the crash, the employer’s business policy may cover your damages.
- Vehicle Owner Liability: If the driver operated someone else’s car with permission, the vehicle owner’s liability policy typically acts as primary coverage.
Steps to Take Immediately After an Uninsured Driver Crash
Protecting your injury claim after a collision with an uninsured motorist requires decisive action:
- Call 911 Immediately: Ensure responding law enforcement officers document that the driver failed to provide valid proof of insurance.
- Document the Scene: Take photos of vehicle damage, road conditions, skid marks, license plates, and visible physical injuries.
- Seek Prompt Medical Care: Visit an emergency room or doctor right away to establish an official medical record linking your injuries to the crash.
- Notify Your Insurer, But Avoid Recorded Statements: Report the collision to your provider promptly, but avoid giving recorded statements until you speak with an attorney. Your insurance carrier becomes your financial adversary during a UM claim.
- Contact a Georgia Car Accident Attorney: Partnering with an attorney ensures your insurer pays the full value of your policy rather than forcing a lowball settlement.
Frequently Asked Questions
Will filing an Uninsured Motorist claim raise my auto insurance rates in Georgia?
Under O.C.G.A. § 33-9-40, Georgia law prohibits insurance companies from surcharging your premium or canceling your policy solely because you were involved in an accident where you were not at fault. However, insurers sometimes attempt improper rate adjustments or misclassify claims, making it vital to have an attorney handle your claim communications.
What happens if the at-fault driver fled the scene (Hit and Run)?
A hit-and-run crash is treated similarly to an uninsured driver claim in Georgia. If law enforcement cannot locate the fleeing driver, your Uninsured Motorist (UM) coverage kicks in to cover your medical bills, lost income, and property damage.
What if the uninsured driver was working at the time of the crash?
If the driver was on the job, driving a company vehicle, or making a delivery when the crash happened, the employer’s commercial insurance policy may provide coverage separate from the driver’s own lack of insurance. An attorney can investigate the driver’s employment status and pursue the employer’s policy where it applies.
How long do I have to file a claim after an uninsured driver accident in Georgia?
Most Georgia personal injury claims must be filed within two years from the date of injury, but some cases may involve different rules or shorter notice requirements. Auto insurance policies also contain strict notification deadlines, sometimes as short as 30 to 60 days, to qualify for UM benefits. Missing these policy notice windows can forfeit your right to coverage.
Protect Your Legal Recovery with Seay/Felton LLC
Dealing with an uninsured driver should not leave you facing mountain-high medical bills alone. The legal team at Seay/Felton LLC Trial Lawyers knows how to investigate complex insurance policies, stand up to uncooperative insurance adjusters, and demand the financial payout you need to move forward.
Injured by an uninsured or underinsured driver in Metro Atlanta, Macon, Savannah, Warner Robins, or anywhere in Georgia? Call Seay/Felton LLC today or fill out our online contact form to schedule your free, confidential consultation.